Home » Earn & Lending
No bank-run risk in DeFi - fixed-term lending on SmartCredit.io protects lenders - SmartCredit.io

No Bank-Run Risk: Why Fixed-Term DeFi Lending Protects Lenders Better Than Aave

Fixed-term DeFi lending eliminates bank-run risk by design: lenders lock funds for a set period and cannot withdraw early, so there is no queue to trigger a cascade. SmartCredit.io’s fixed-term model means lender capital cannot exit mid-term, liquidations return collateral to borrowers at 0% fee, and the Loss Provision Fund covers any residual shortfall. Lenders earn fixed interest income plus weekly SMARTCREDIT token rewards with no variable-rate surprises.
Portfolio MCP on SmartCredit.io - AI portfolio optimization via Claude and Model Context Protocol

Portfolio MCP: AI-Managed Crypto Portfolio Optimization via Claude

Portfolio MCP connects Claude AI to SmartCredit.io’s portfolio optimisation engine via the Model Context Protocol. Describe your DeFi goals in plain language – target yield, risk tolerance, sector exposure – and receive a Markowitz-optimised allocation backed by live CoinGecko data and historical rate analysis. The first DeFi lending platform to expose an MCP server, letting AI assistants run institutional-grade portfolio construction without manual calculations.

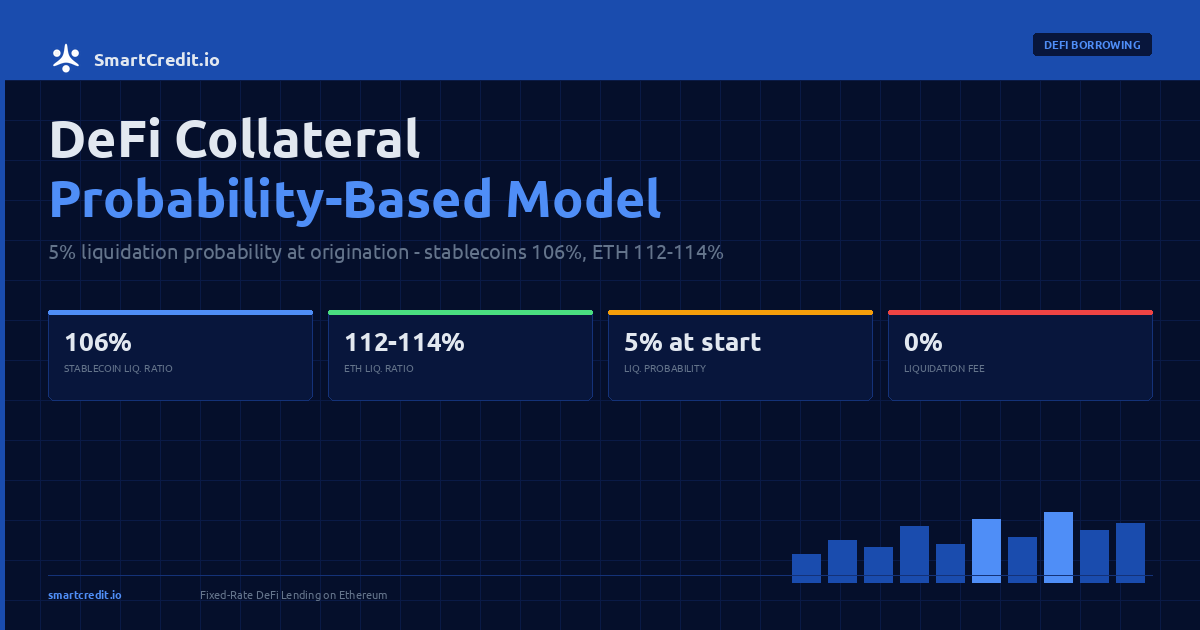
DeFi collateral ratio by probability model on SmartCredit.io - 106% stablecoins, 112% ETH - SmartCredit.io

DeFi Collateral Ratio Explained: How SmartCredit.io Uses Probability to Set Your Borrowing Buffer

Most DeFi platforms set collateral ratios by governance vote or hardcoded asset tiers. SmartCredit.io calculates collateral requirements from a probability model: each loan starts at a 5% liquidation probability, with longer terms requiring more buffer to account for extended volatility exposure. Simple mode selects collateral automatically; Advanced Borrowing mode lets experienced users adjust within safety bounds. This post explains how probability-based collateral works and why it is more capital-efficient than fixed-ratio alternatives.

SmartCredit.io vs Aave 2026: fixed-rate vs variable DeFi lending platform comparison

SmartCredit vs Aave 2026: Fixed-Rate vs Variable DeFi Lending Compared

SmartCredit vs Aave in 2026: two fundamentally different lending models. Aave offers variable rates, earns 5-10% on every liquidation, and has no built-in warning system. SmartCredit.io offers fixed rates, earns 0% on liquidations, and returns remaining collateral to borrowers. Full comparison of rates, collateral ratios, lender yield, borrower protection and Loss Provision Fund vs Aave’s safety module.

Why Aave and Compound have no liquidation monitor - conflict of interest explained - SmartCredit.io

DeFi Liquidation Monitor: Why Aave Has No Warning System and SmartCredit.io Built One

Aave, Compound and MakerDAO earn 5-10% on every liquidation and run their own liquidation bots – so building a warning system that reduces liquidations would directly cut their revenue. SmartCredit.io earns 0% on liquidations and built the Protection Agent: a tool that monitors Aave V3 and Compound V3 positions, models liquidation probability from collateral volatility, and sends Telegram alerts before the health factor falls below 1.0. No wallet connection required.

DeFi liquidation fee comparison: Aave charges up to 10%, SmartCredit.io charges 0% - SmartCredit.io

DeFi Liquidation Fee Exposed: Why Aave Takes Up to 10% and SmartCredit.io Charges 0%

DeFi liquidation fees cost borrowers 5-10% of their collateral on Aave, Compound and MakerDAO – taken by protocol-run bots that profit from every liquidation event. SmartCredit.io charges 0% on liquidations and returns remaining collateral to the borrower’s credit line. This post explains why the fee exists, how it compounds losses during volatile markets, and what a zero-fee model changes for DeFi borrowers.

Institutional crypto lending on SmartCredit.io - fixed-rate DeFi for funds, DAOs and protocols - SmartCredit.io

Institutional Crypto Lending: Why Fixed-Rate DeFi Serves Funds and Protocols in 2026

Institutional crypto lending requires predictable costs, transparent liquidation rules and credible lender protection – none of which variable-rate protocols reliably provide. SmartCredit.io’s fixed-rate, fixed-term model on Ethereum gives funds, DAOs and corporate treasuries a locked rate from day one, 0% liquidation fees, and a Loss Provision Fund that covers shortfalls if liquidation proceeds fall short. No governance surprises, no rate spikes mid-term.

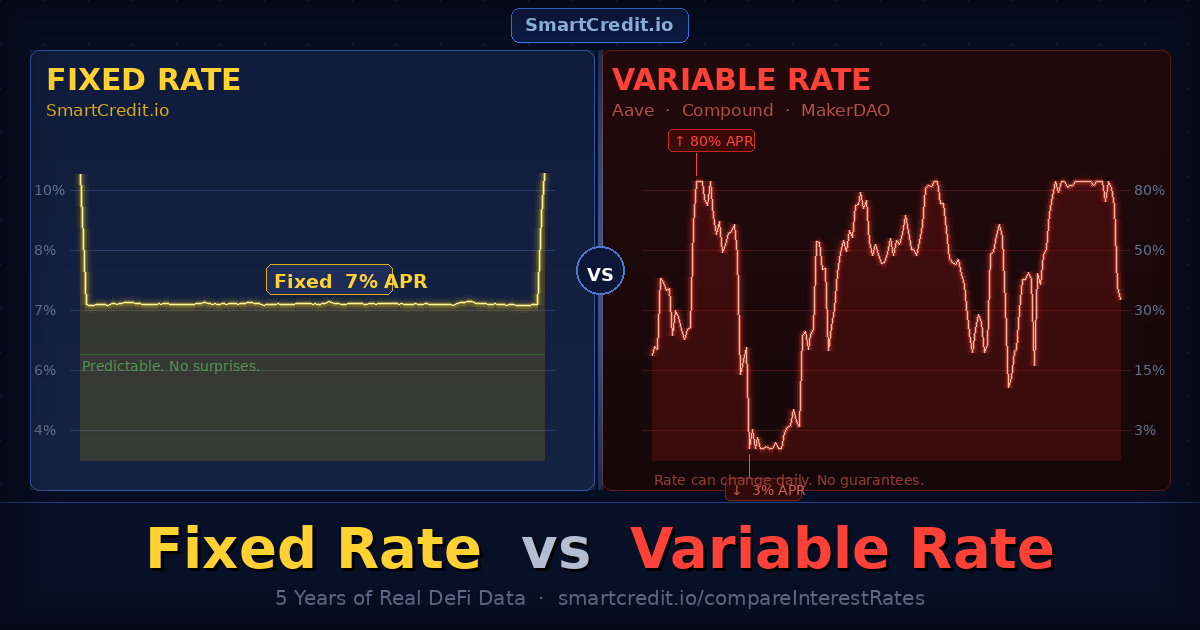
DeFi interest rates comparison chart showing fixed rates from SmartCredit vs volatile variable rates from Aave, Compound and MakerDAO over 5 years

DeFi Interest Rates Comparison: Why Fixed Rates Win for Real-Economy Borrowers

Fixed vs variable DeFi rates: SmartCredit.io offers 8-15% fixed APY (predictable) vs Aave/Compound 3-35% variable (volatile). Real data (5-year analysis): Aave USDC rates ranged 3.2% to 38.7% (1,109% volatility). SmartCredit fixed rates: 8-12% (0% volatility). Who benefits from fixed: (1) Real-economy borrowers – budgeting requires certainty, (2) Traders – leveraged positions need predictable costs, (3) Lenders – stable income planning. Who needs variable: Speculators timing short-term rate dips. March 2025 example: Variable rates spiked 12% → 35% in 48 hours. Fixed users locked 10%, saved 25%. Immunebytes audited, non-custodial. Visit

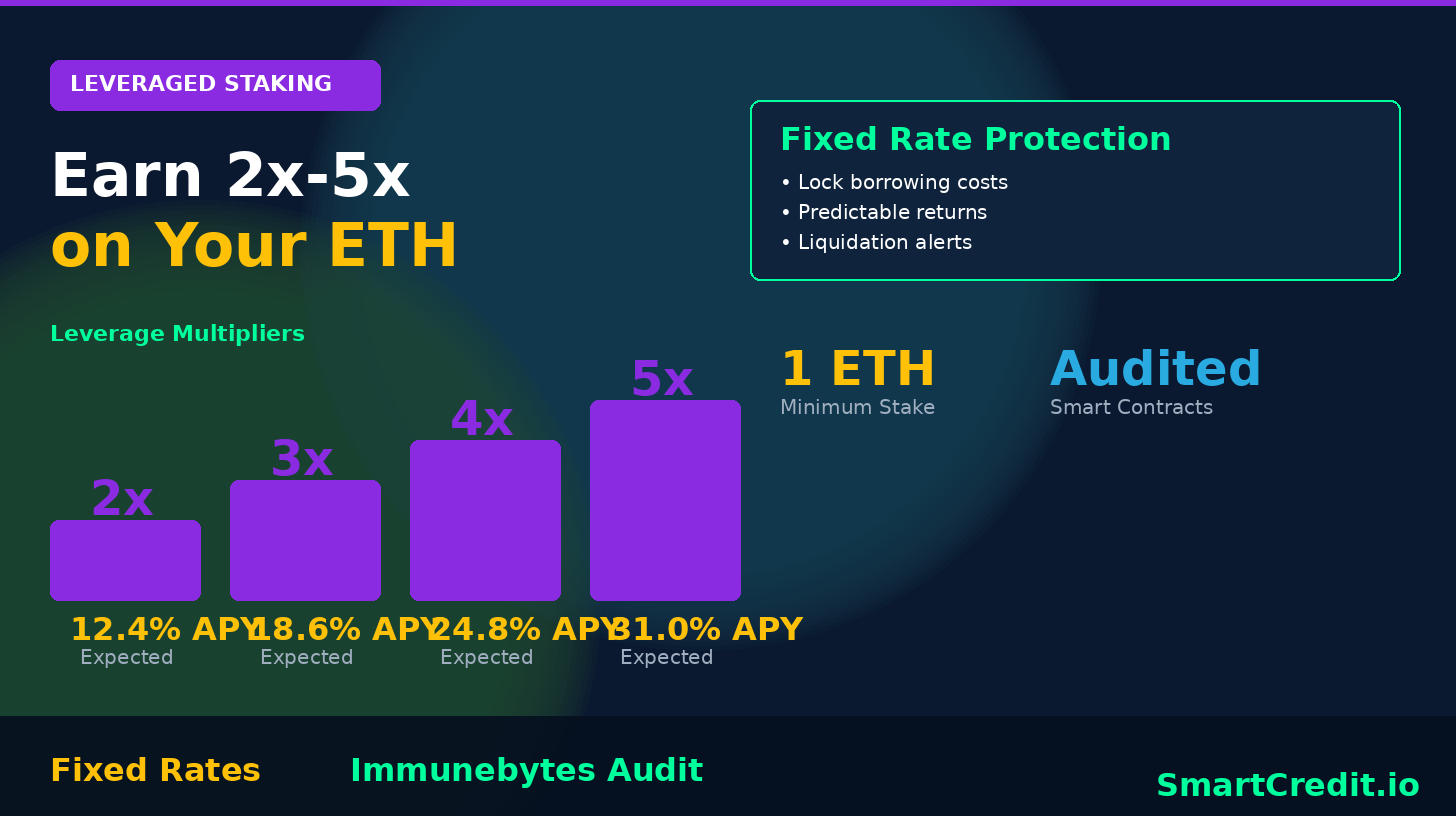
Leveraged Lido Staking with Fixed Rates: Earn 2x–5x on Your ETH (2026)

Leveraged Lido staking amplifies ETH returns 2x-5x: deposit 1 ETH on SmartCredit.io, borrow 1 ETH at 10% fixed APY, stake 2 ETH with Lido earning 6.2% APY. Net yield: (2 × 6.2%) – 10% = 2.4% (vs 6.2% unleveraged). At 5x leverage: deposit 1 ETH, borrow 4 ETH, stake 5 ETH. Yield: (5 × 6.2%) – (4 × 10%) = -9% (negative, too risky). Optimal leverage: 2-3x. Risk: liquidation if ETH drops >20%. Protection: fixed borrow rates (10% locked), liquidation probability calculator, position alerts. Minimum 1 ETH, Immunebytes audited smart contracts. Start conservative, increase leverage as comfortable. Visit /lend

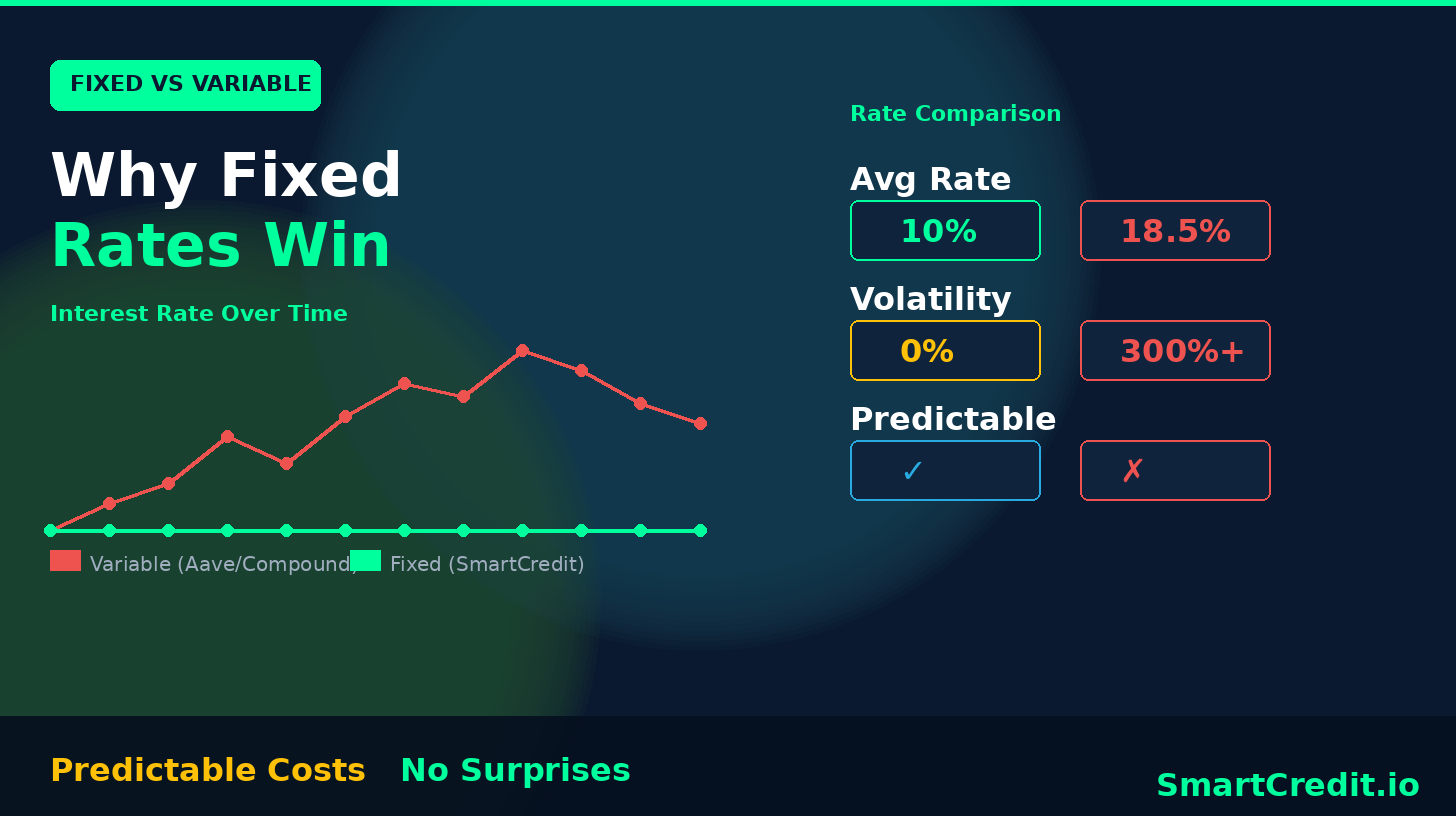
Fixed Interest Rate vs Variable Interest Rate in DeFi: Why Fixed Rates Win (2026)

Traditional fixed income ($100T+ global market) is 10x larger than money markets ($10T). Yet DeFi inverted this: variable-rate lending dominates (Aave, Compound $20B+ TVL) while fixed-rate barely exists. Why fixed rates win: (1) Budgeting certainty – businesses need predictable costs, (2) Risk management – volatile rates destroy profitability, (3) Institutional adoption – pensions/endowments require stable returns. SmartCredit.io brings traditional finance structure to DeFi: 8-15% fixed APY, 30-365 day terms, non-custodial. Historical proof: March 2025, variable rates spiked 300%+. Fixed users unaffected. The future: DeFi fixed income will surpass variable as institutions arrive. Immunebytes audited. Visit

How to Make Money with DeFi in 2026: 9 Proven Strategies (With APY Ranges)

Make money with DeFi in 2025: 9 proven strategies. (1) Fixed-rate lending on SmartCredit.io – 8-15% APY, zero risk of principal loss, (2) Staking – ETH 6.2% APY, stablecoins 5-8%, (3) Liquidity providing – Uniswap 15-40% APY (impermanent loss risk), (4) Yield farming – Curve 12-25% APY, (5) Leveraged staking – 2-5x returns (high risk), (6) Arbitrage – DEX spreads 0.5-2%, (7) Lending aggregation – auto-optimize across platforms, (8) Options selling – 10-30% APY (advanced), (9) Referrals – SmartCredit pays 50% fees forever. Risk ratings: Low (lending, staking), Medium (LP, farming), High (leverage, options). Start conservative, scale up. Visit

Best Crypto Lending Platforms 2026: Earn Up to 18% APY with DeFi

Best crypto lending platforms 2025: $20B+ earns 8-18% APY globally. SmartCredit.io: 8-15% fixed APY, non-custodial (you control keys), 90% LTV, Immunebytes audited, 5-year zero-hack record. Aave: 3-12% variable APY, $10B TVL, battle-tested. Compound: 4-10% variable, institutional backing. MakerDAO: 5-8% DAI Savings Rate, oldest DeFi protocol. Comparison: SmartCredit wins on predictability (fixed rates), Aave wins on liquidity ($10B), Compound wins on simplicity. Risk factors: smart contract bugs (audit mitigation), oracle manipulation (use Chainlink), liquidation (maintain 150%+ ratio). How to start: deposit USDC/DAI, earn automatically, withdraw anytime. Average user: $5K deposit = $600/year passive income. Visit /lend