Home » Earn & Lending » Page 2
Yield Farming

Yield Farming Exposed: Proven Fixed-Rate Strategy That Actually Works

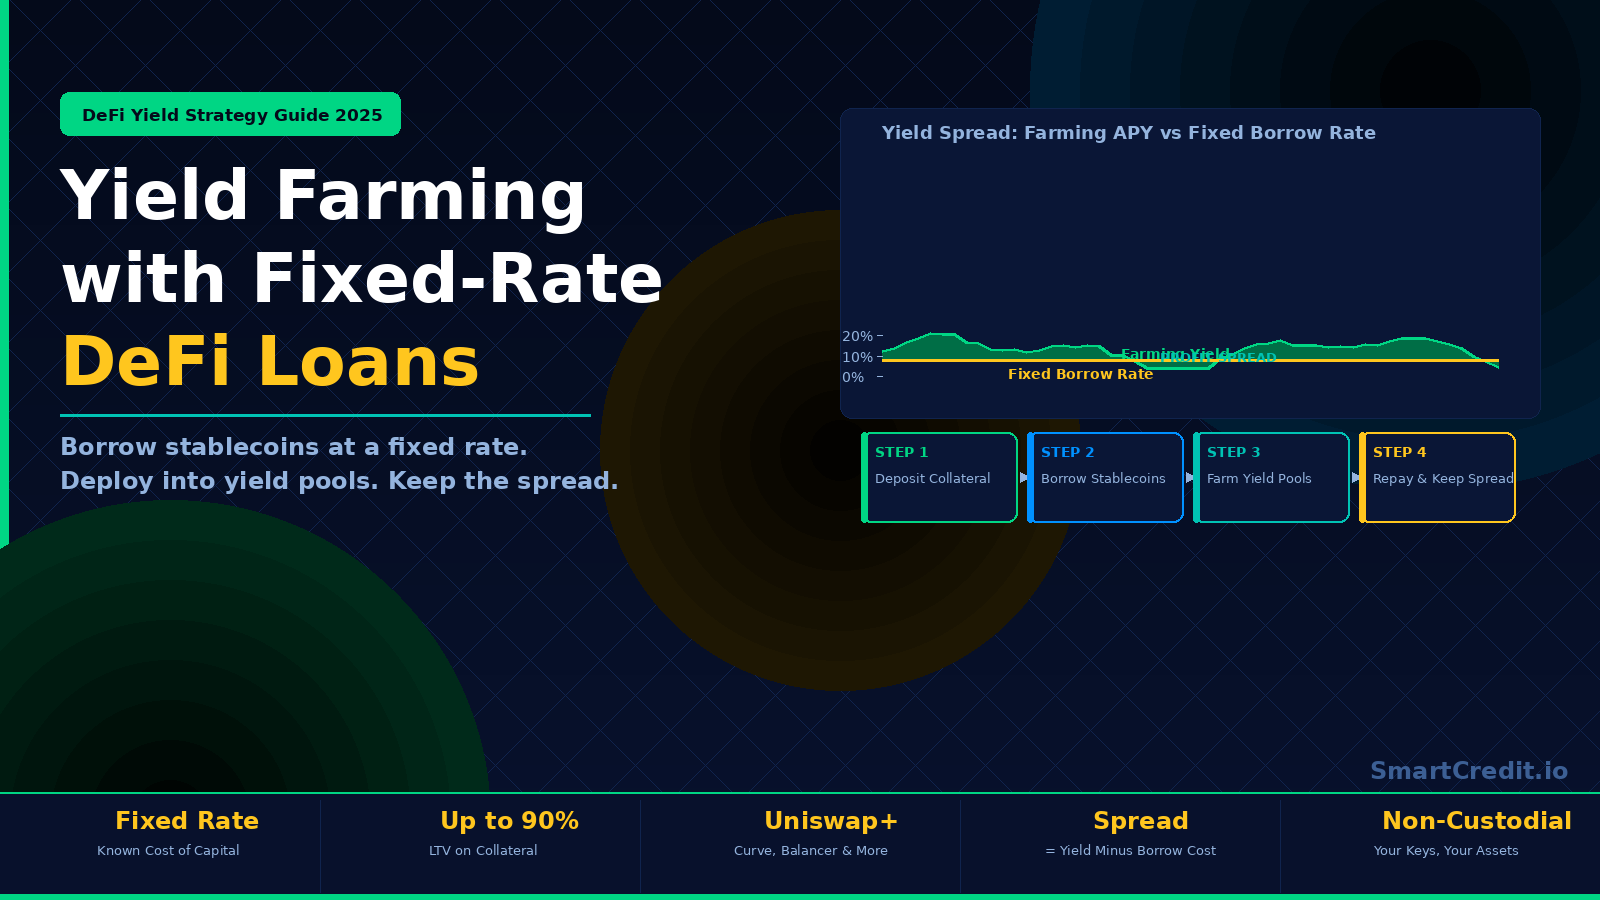
Yield farming with fixed-rate loans: borrow USDC at 10% fixed APY on SmartCredit.io, deploy to Curve USDC/DAI pool earning 15% APY, keep 5% spread as pure profit. Strategy: (1) Deposit $20K ETH collateral, (2) Borrow $18K USDC at 10% APY (fixed), (3) Farm Curve earning 15% APY, (4) Net profit: 15% – 10% = 5% ($900/year) + maintain ETH exposure. Platforms: Curve (stable pools, 10-18% APY), Uniswap V3 (concentrated liquidity, 20-40%), Balancer (multi-token pools, 12-25%). Risk management: fixed borrow rates eliminate rate spike risk (vs Aave variable 5-35%). Calculate: farming APY must exceed borrow APY + 3% safety margin. Immunebytes audited. Visit /borrow
How to earn with SmartCredit.io

How to Earn with SmartCredit.io?

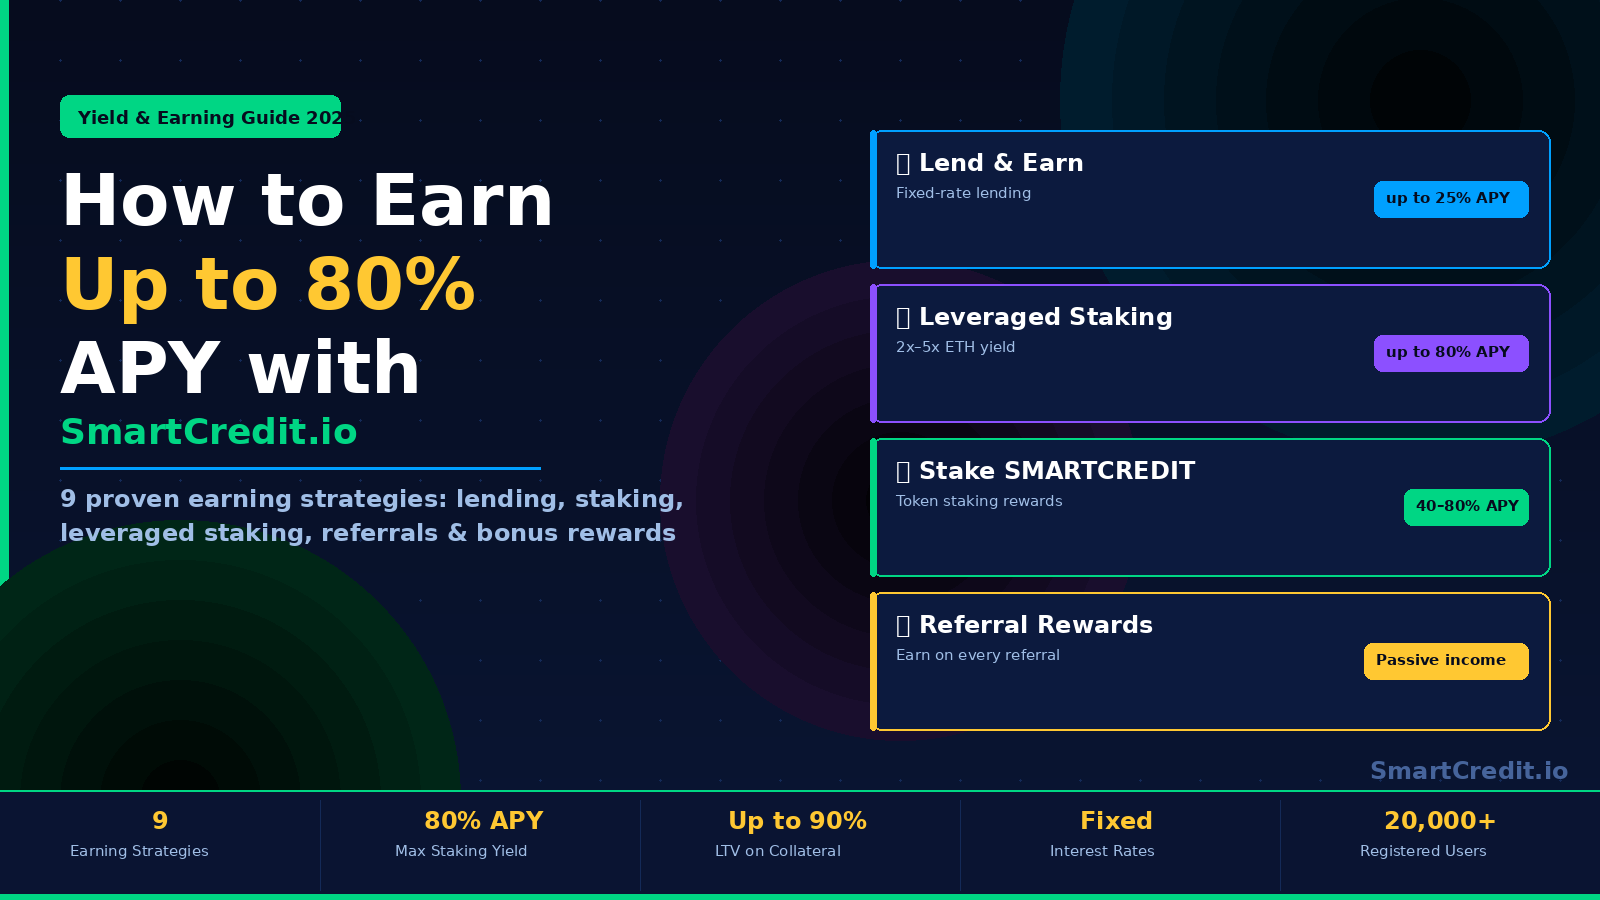
Earn with SmartCredit.io: 9 strategies up to 80% APY. (1) Fixed-rate lending – 8-15% APY on USDC/DAI, zero principal risk, (2) SMARTCREDIT staking – 30-80% APY (decreasing inflation), (3) Liquidity providing – supply both sides of market, (4) Leveraged ETH – 2-3x base staking (12-18% net), (5) Referrals – 50% of loan fees forever + 25 tokens per borrower, (6) Yield farming – fixed-rate loan arbitrage, (7) Bonus rewards – 9.5% APY extra for lenders/borrowers, (8) Credit lines – unlock capital efficiency, (9) Widgets – embed on your site, earn commissions. All non-custodial (you control keys), Immunebytes audited, 5-year track record. Start conservative (lending), scale to advanced (leverage). Visit

Crypto Fixed Income and SmartCredit.io

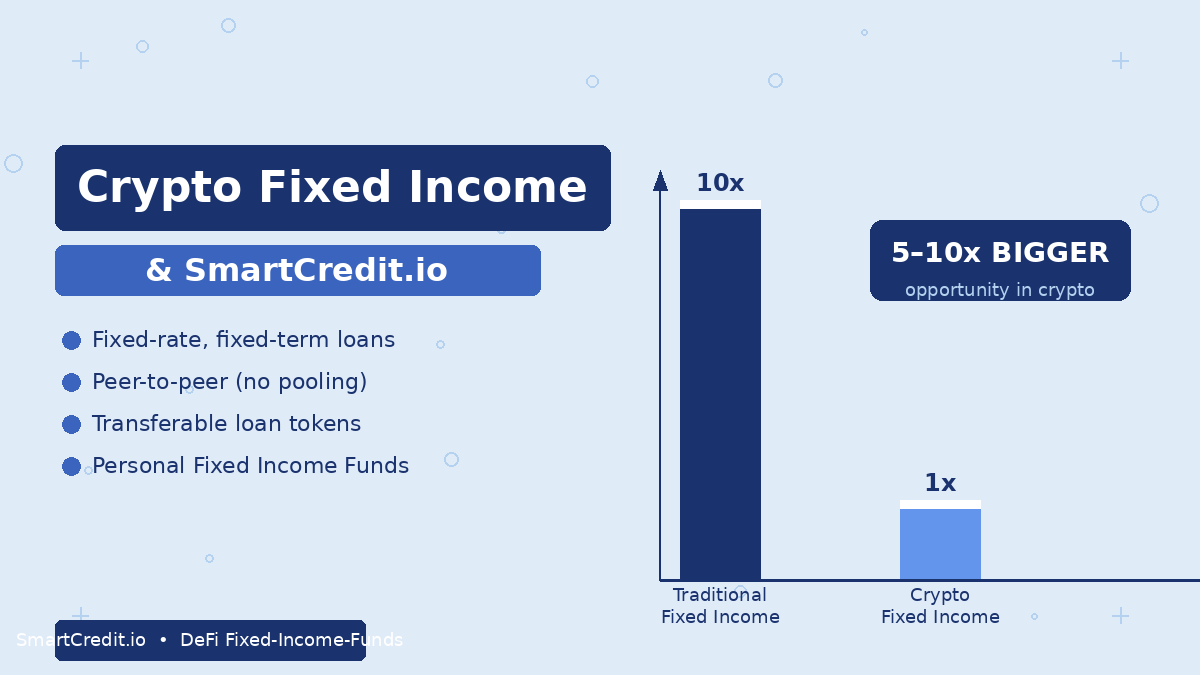
Crypto fixed income paradox: Traditional markets show fixed income 5-10x larger than equities ($100T bonds vs $20T stocks). Yet in crypto, fixed income is 5-10x SMALLER than variable-rate lending. Why? DeFi copied money markets (Aave, Compound) instead of bond markets. SmartCredit.io reverses this: fixed-rate (8-15% APY), fixed-term (30-365 days), peer-to-peer lending mirrors traditional fixed income structure. Advantages: predictable returns for institutions, budgeting certainty for businesses, stable income for retirees. Market opportunity: as crypto matures, institutions demand fixed income. Current: $20B+ variable lending. Future: $200B+ fixed income market. First mover advantage. Immunebytes audited. Visit

What drives the crypto interest rate and how much should it be?

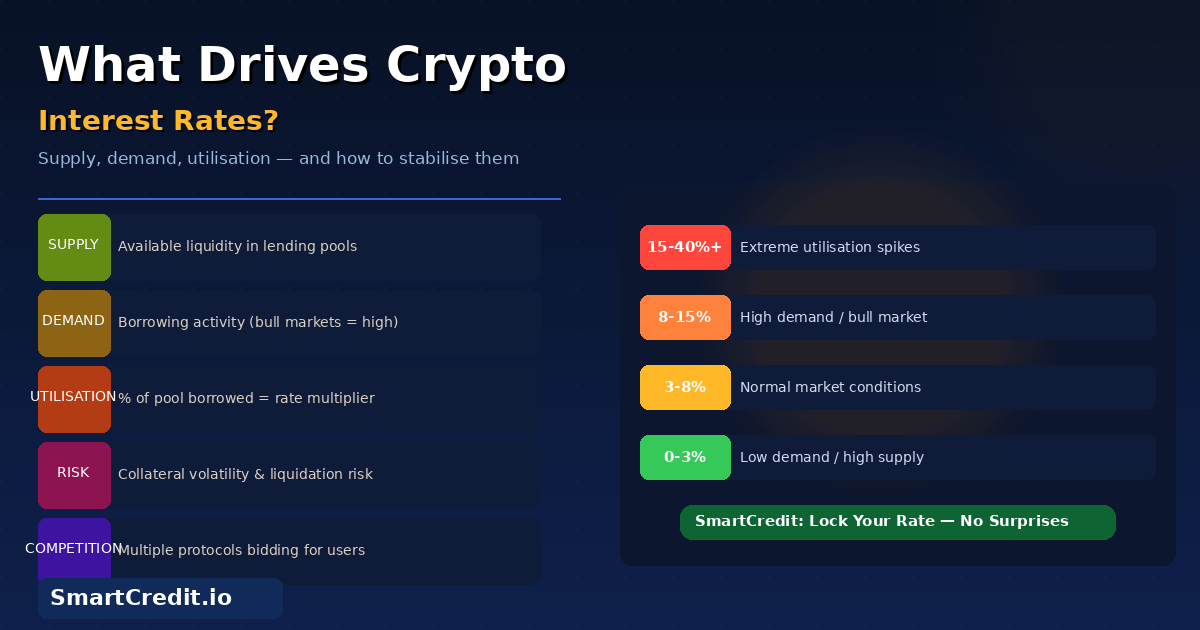
Crypto interest rates (5-18% APY) vastly exceed traditional savings (0.01-1% APY). Why? Five factors drive this: (1) Supply/demand volatility – DeFi borrow rates spike during bull markets as leverage demand surges. (2) Collateralization – 110-150% overcollateralization compensates lenders for crypto price risk. (3) Platform competition – Aave, Compound, SmartCredit.io compete aggressively. (4) Risk premiums – Smart contract risk, liquidation risk. (5) Utilization rates – When 90%+ of pools are borrowed, rates surge. SmartCredit.io offers 8-15% fixed APY (predictable) vs Aave/Compound 3-25% variable (volatile). Historical data: ETH averaged 12.3% on SmartCredit vs 9.8% on Aave. Visit

What Drives the Fiat Interest Rate and How Much Should it Be?

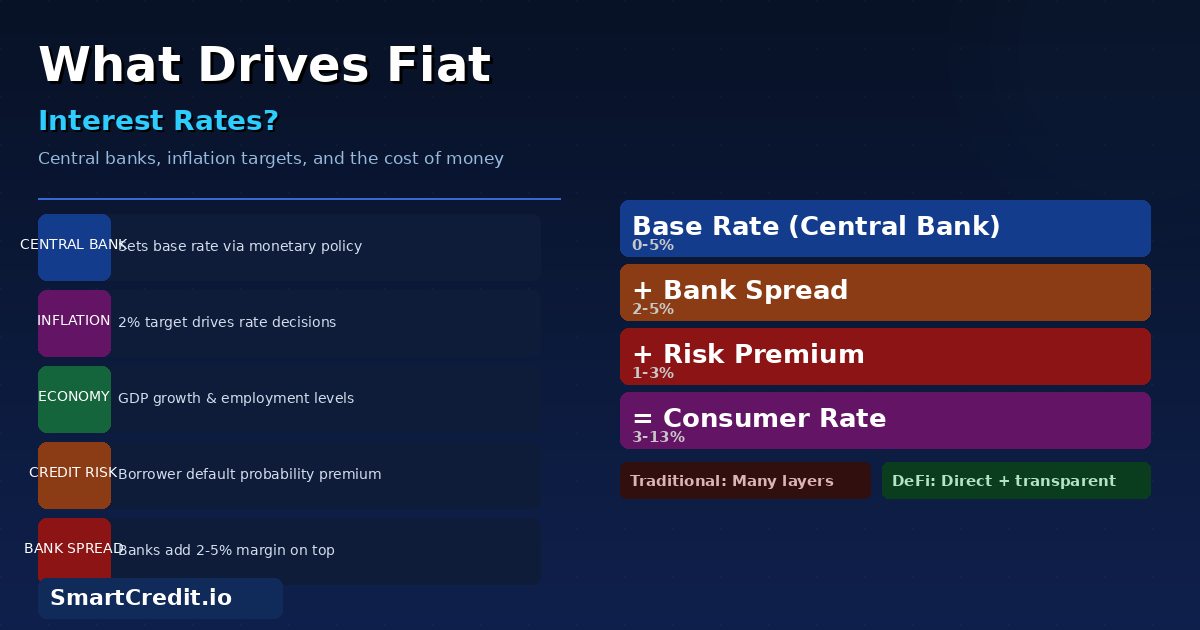
Fiat savings accounts pay 0.01-5% APY (US: 0.5-1% typical). Why so low? Central banks suppress rates, fractional reserve banking limits competition, government guarantees (FDIC) reduce risk premiums. Crypto interest offers 8-18% APY because: (1) No central bank manipulation, (2) Market-driven rates, (3) Overcollateralization (110-150%), (4) Platform competition. SmartCredit.io: 8-15% fixed APY on USDC/DAI deposits, Immunebytes audited, 5-year zero-hack record. Real comparison: $10,000 at 0.5% fiat = $50/year. $10,000 at 12% crypto = $1,200/year. That’s 24× more income. Risk differences: Fiat = government guaranteed, crypto = smart contract risk. Visit /lend